Analysis · From access to economic opportunity
From Payment Rails to Economic Rails
Reusing digital building blocks for firms and public services
A shared payment rail can reduce repeated integration effort. Its broader development value depends on the services institutions can safely build and sustain around it.
The argument
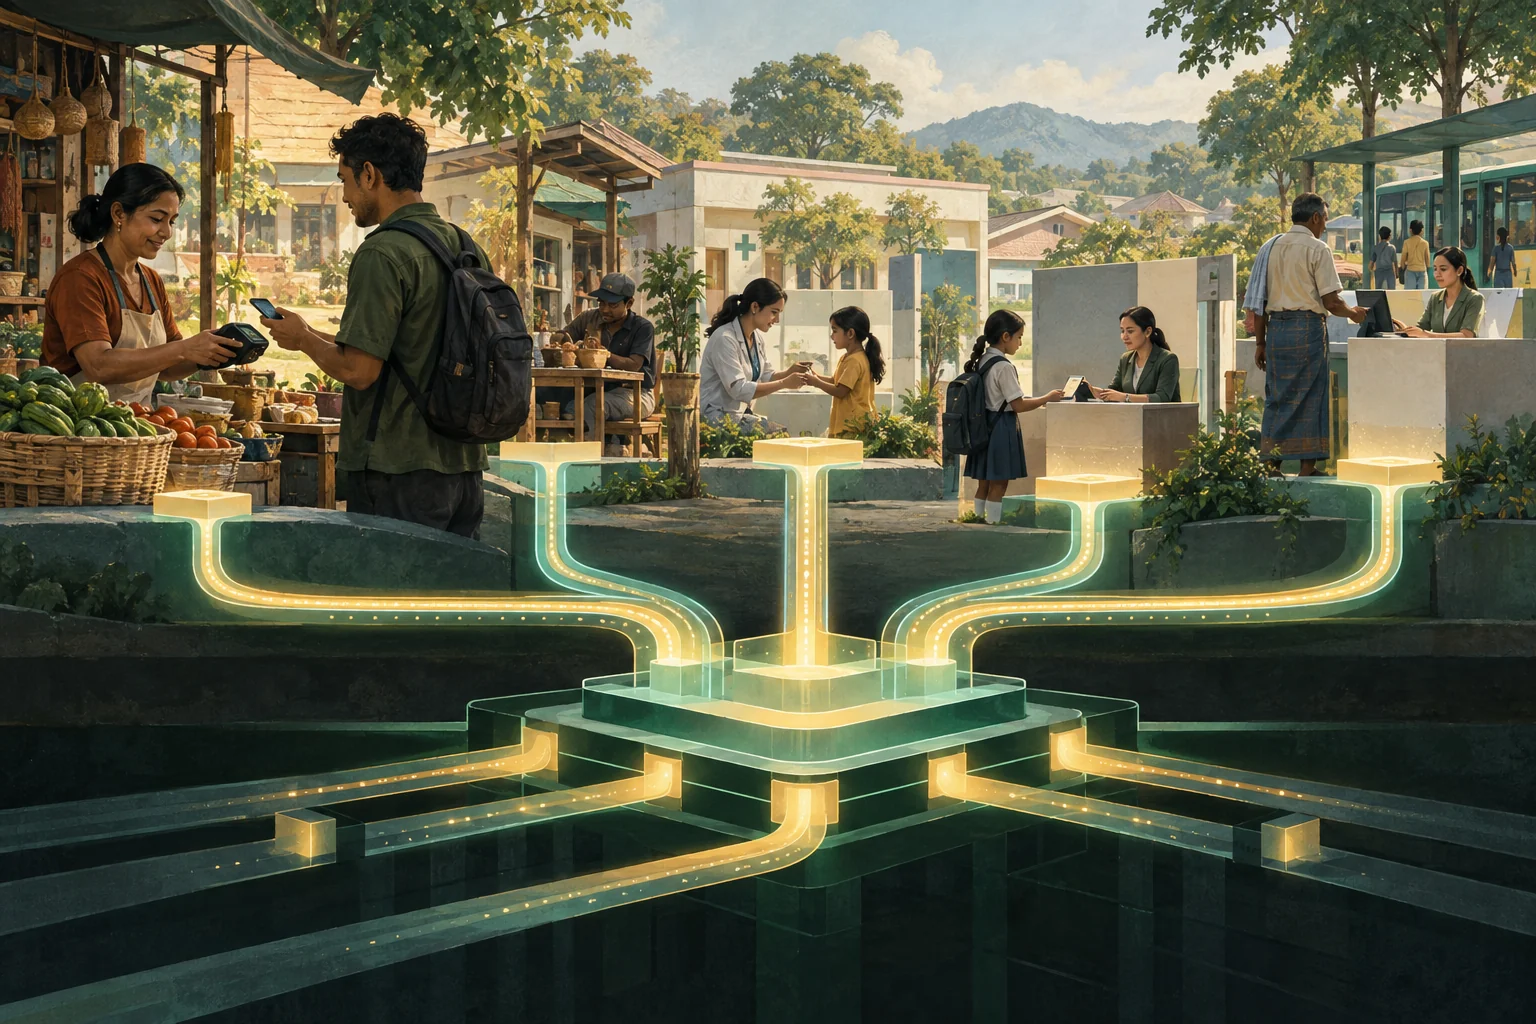
GIMACPAY's experience makes reuse a concrete design question. The same regional connections can support different payment journeys involving merchants, financial institutions, remittance partners and public bodies. A new service can potentially draw on existing connectivity instead of negotiating every institutional link again. The economic benefit is a reduction in duplicated work, conditional on compatible rules and a viable service model.
I use the idea of economic rails to describe this capacity for reuse. It does not mean that a payment switch becomes the entire digital economy. Firms still need customers, logistics, electricity and finance. Public institutions still need reliable registers and accountable administrative processes. Payments provide one essential function within a wider system of digital identity, trusted data exchange and sector-specific services.
The World Bank's 2025 DPI approach describes reusable digital building blocks for public benefit [B]. This provides a useful distinction between a shared foundation and an individual application. The foundation should enable different providers and services without making every innovation dependent on exclusive arrangements with one commercial platform. Public benefit depends on governance and access conditions as well as technical architecture.
Consider government collections as a prospective application. A payment confirmation only becomes useful administrative evidence when it is linked to the correct payer, obligation, and accounting record. The ongoing Central African Treasury integration work illustrates the institutional questions involved; it should not be described as a completed nationwide transformation. Reuse can accelerate payment connectivity, while public financial management reform must address reconciliation, controls and staff responsibilities.
The governance challenge resembles a shared-resource problem: many providers can benefit from a common foundation, while some prefer to retain exclusive customer relationships. Technical reuse will remain limited if access agreements reproduce those incentives. The design should therefore examine who controls interfaces, who pays for maintenance, and whether new entrants can build a service without negotiating discretionary permission from every incumbent.
From question to implementation
Data reuse creates another opportunity and another boundary. A firm's transaction history may help a lender understand cash flows, but it does not establish creditworthiness by itself. Cash sales, seasonality, shared accounts, and platform dependence can distort the picture. Lawful access, appropriate consent where required, data correction and scrutiny of discriminatory proxies are prerequisites for responsible financial services.
The proposed framework distinguishes shared functions from the services and outcomes they may enable. That distinction keeps the development argument testable. For example, lower integration costs can be measured through time and expenditure; improved merchant sales or government revenue efficiency need additional evidence. Open interfaces can widen entry, but competition also depends on pricing, settlement access, and contractual terms.
A global application would start with a small set of priority journeys, identify which functions can be reused, and protect choice at the service layer. Governments and development partners can support common standards and early institutional capacity. Private firms can then compete on products and service quality. Procurement should preserve portability so that common infrastructure does not become a new source of vendor dependence.
Reuse and development value
| Dimension | Implementation question | Evidence to track |
|---|---|---|
| Shared function | Payment, identity or lawful data exchange | Access rules and interoperable interfaces |
| Service layer | Commerce, collections or financing | Provider choice and sector accountability |
| Result | Lower friction or better delivery | Baseline and outcome-specific evaluation |
Implications for practice
- Select priority services whose integration burden and public value can be measured.
- Keep data-enabled finance conditional on lawful access, quality and fair decision processes.
Evidence & sources
Evidence and source note GIMACPAY service portfolio in my practitioner notes; Treasury integration remains ongoing in the available project record. DPI definition and reuse context: [B]. Proposed financing uses are not reported results.
These are practitioner reflections, not peer-reviewed impact studies or an official GIMAC or World Bank position. GIMAC figures come from the supplied notes and remain attributed to their reporting scope. New frameworks and diagrams are analytical proposals; they have not been validated as causal models. Approval, deployment, active use and economic impact are kept distinct.